Fix & flip financing
Fix & Flip Loans in New York, New Jersey and Connecticut
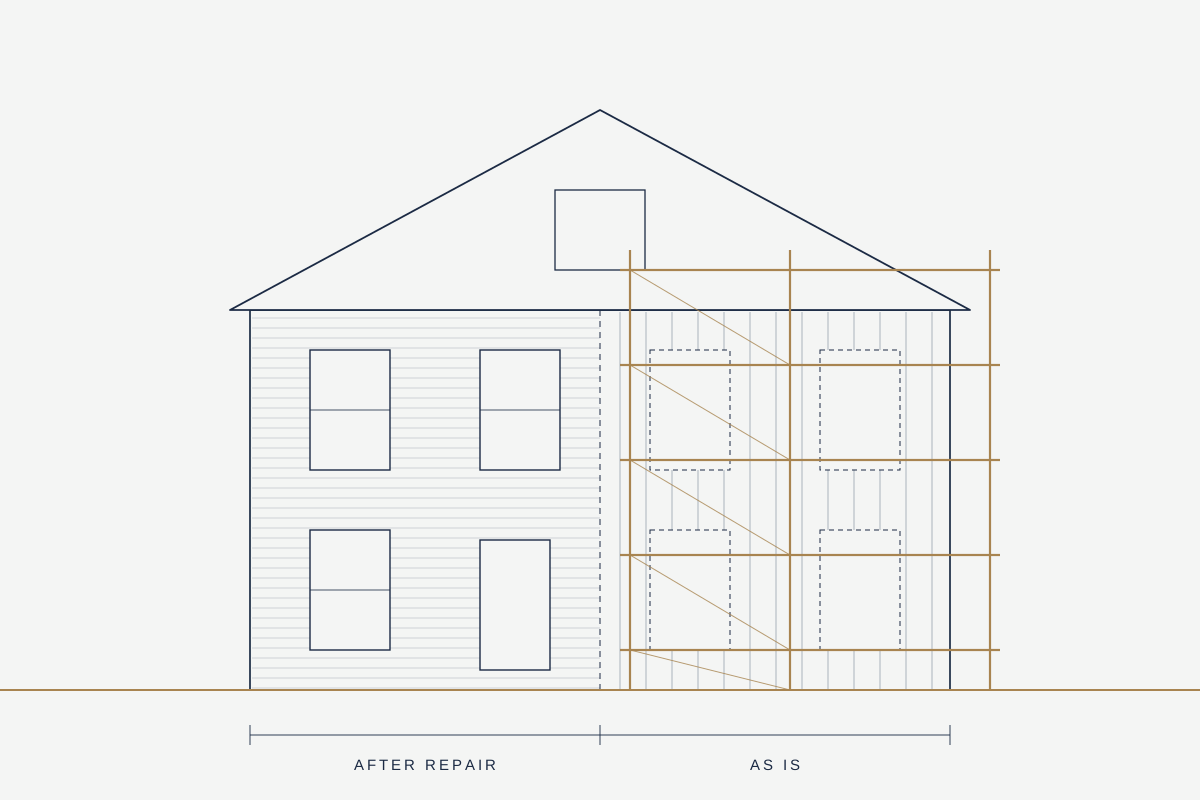
Financing to buy a property that needs work, fund the renovation in draws, and repay the loan when you sell. Built for investors who have the deal and need capital structured around the project.
At a glance
Program details are confirmed on every quote. From Wisdom Capital's program guidelines; subject to underwriting and final approval.| Purpose | Purchase and renovation of investment property for resale |
|---|---|
| Markets | New York (NYC, Long Island, Westchester), New Jersey, Connecticut |
| Borrowers | New and experienced investors; no minimum number of completed flips. Must close under an LLC or corporation |
| Property types | 1–4 unit residential |
| Leverage | Up to 90% of purchase price and up to 100% of hard costs, capped at 70% of ARV; loans $100,000 – $3,000,000 |
| Renovation funds | Released in draws: send photos or video of completed work, same-day wire, no on-site inspections |
| Payments | Interest-only during the term |
| Term | 1-year, interest-only; 3-month minimum, then month-to-month up to 12 months |
| Valuation | $495 desktop appraisal; no property access needed |
| Credit | No minimum credit score |
| Attorney fee | $1,950 purchase only; $2,350 purchase + construction |
| Rate and points | 10.99% for qualified investors; 2 points |
How a flip loan works
Four moving parts to understand before you sign a contract.
The purchase advance
At closing, the lender funds a share of the purchase price. You bring the balance plus closing costs and points. This is usually the largest piece of cash you need.
The renovation draws
Wisdom Capital funds up to 100% of hard costs against the scope of work you submit at closing. Finish a phase, send photos or video, and the draw can be wired the same day. You need enough cash to start each phase.
The leverage
Wisdom Capital lends up to 90% of the purchase price and up to 100% of hard costs, on loans from $100,000 to $3,000,000. The total loan is also capped at 70% of your after-repair value, and ARV is your exit and your profit. See what LTC means and how to calculate ARV.
The exit
The loan is repaid from the sale. Underwriting looks at whether your ARV is supported by recent comparable sales and whether the timeline is realistic for the scope.
What to prepare for a fix-and-flip loan
- Signed purchase contract, or the price and terms you expect to agree on
- A line-item scope of work and renovation budget
- Three to five recent comparable sales that support your ARV
- Your project history: addresses, purchase and sale prices, timelines (if any)
- Proof of funds for the down payment, closing costs and reserves
- The entity you will buy in, such as an LLC, and its formation documents
The full list, and why each item matters, is in hard money loan requirements.
Where flip budgets usually go wrong
Most financing problems on flips trace back to three numbers: an ARV based on the best sale in the neighborhood rather than typical ones, a renovation budget without a contingency, and a timeline that ignores permits, inspections and the time to sell. Build the deal around conservative versions of all three and the financing conversation gets simpler.
Underwrite the project the way the lender will: the lower of cost and value, and the longer of your timelines.
Fix & flip loan FAQ
How much can I borrow for a fix and flip?
Wisdom Capital lends up to 90% of the purchase price and up to 100% of hard (renovation) costs, from $100,000 to $3,000,000. The loan is also capped at 70% of ARV. A $400,000 purchase with a $100,000 renovation and a $700,000 ARV could be financed up to $460,000. Try your numbers in the loan calculator.
Does the loan cover 100% of the renovation?
Wisdom Capital covers up to 100% of hard costs, released in draws as each phase is completed. You still need cash to start each phase before its draw.
How much cash do I need for a flip?
Plan for the portion of the purchase price not financed, closing costs and points, the cash to start renovation phases before each draw, monthly interest, holding costs, and a contingency reserve. The calculator totals these for you.
Can I get a fix and flip loan with no experience?
Often, yes, with more emphasis on the deal and your liquidity. See first-time investor financing and what lenders weigh on a first deal.
Next step
Have a Flip Under Contract?
Send the address, price, scope and ARV, and let’s review how the financing could be structured.
Helpful to include
- Property address and property type
- Purchase price and target closing date
- Renovation budget or scope of work
- Estimated after-repair value (ARV) and comps
- Your recent project experience, if any